Taxation and Online Casino Winnings in Canada
§ 25.19 · Marc-André Fortin ·
Recreational casino winnings are not taxed in Canada. That’s the CRA’s long-standing position, rooted in paragraph 40(2)(f) of the Income Tax Act, which treats a win on a bet or lottery scheme as a nil capital gain. In the US, the IRS withholds 30% on winnings over USD 1,200. The exception is gambling run as a business, and a Federal Court of Appeal ruling against three professional poker players sharpened exactly where that line sits. If you gamble casually, your winnings stay yours. If you gamble for a living, the CRA now has a clearer path to tax you.
Recreational Winnings Are Tax-Free Under Paragraph 40(2)(f)
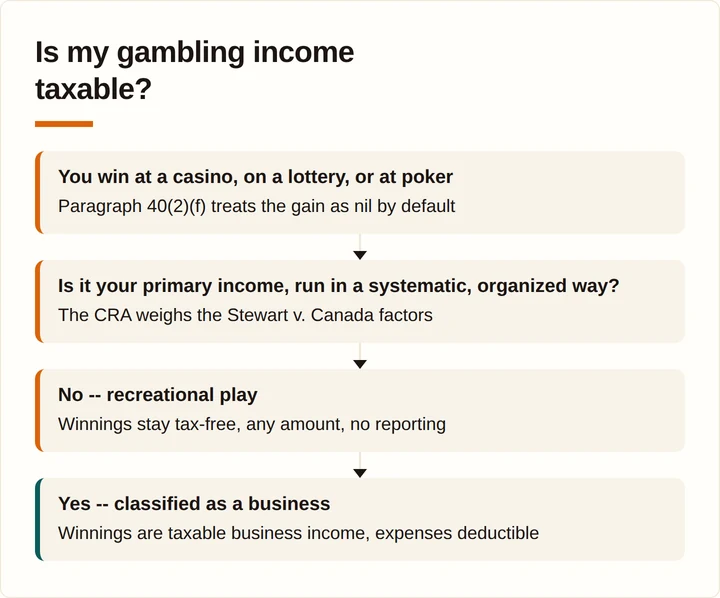
The statutory basis for tax-free recreational gambling is paragraph 40(2)(f) of the Income Tax Act. It states that a taxpayer’s gain from the disposition of a chance to win a prize or bet, or a right to receive an amount as winnings on a bet, in connection with a lottery scheme, is nil. A nil gain means no taxable income. For casual players, that statutory rule settles the question.
The CRA’s general guidance aligns with this. A casual lottery ticket, a friendly poker game, a slot session at an Ontario casino triggers no tax on winnings. The Act itself says the gain is zero. You don’t report it, and you don’t pay tax on it.
This treatment traces back to *Minister of National Revenue v. Morden* (1961), where the Exchequer Court held that gambling gains are taxable only when derived from carrying on a business. That case established the business-versus-windfall distinction that still governs today. A windfall is an unexpected, non-recurring gain. Business income is the product of an organized commercial activity.
The CRA doesn’t care how often you play or how much you win, as long as gambling isn’t how you make your living. Winning CAD 50,000 on a single slot spin doesn’t make you a professional. It makes you lucky. The tax treatment stays the same.
When Gambling Becomes a Business: the Fournier-Giguère Ruling
The line between recreational and professional got sharper in 2025. In *Fournier-Giguère v. Canada*, 2025 FCA 112, the Federal Court of Appeal upheld Tax Court rulings against three professional poker players. They owed tax on roughly CAD 1.7 million in combined winnings over four years. The Supreme Court of Canada refused leave to appeal in June 2026, making this the current word on professional-gambler taxation.
The Court applied the *Stewart v. Canada* framework, weighing intention to profit, commercial organization of the play, sustained profitability, financial dependence, systematic high-volume play, and lifestyle evidence.
The players in *Fournier-Giguère* lost because they looked like professionals in every measurable way. They played high volumes, organized their schedules around poker, relied on winnings for living expenses, and showed sustained profits. That’s what makes it a business.
The CRA applies the same factors in plainer terms, checking whether you:
- Gamble as your main source of income
- Run your play in a systematic, organized way
- Show a profit over multiple years
- Depend on gambling earnings to pay your bills
Recreational players keep their tax-free treatment. *Fournier-Giguère* clarifies where the professional line sits, leaving recreational tax-free treatment untouched. If you gamble for fun with money you can afford to lose, the Act’s nil-gain rule still protects you.
Interest on Your Winnings Is Taxable, Even If the Win Wasn’t
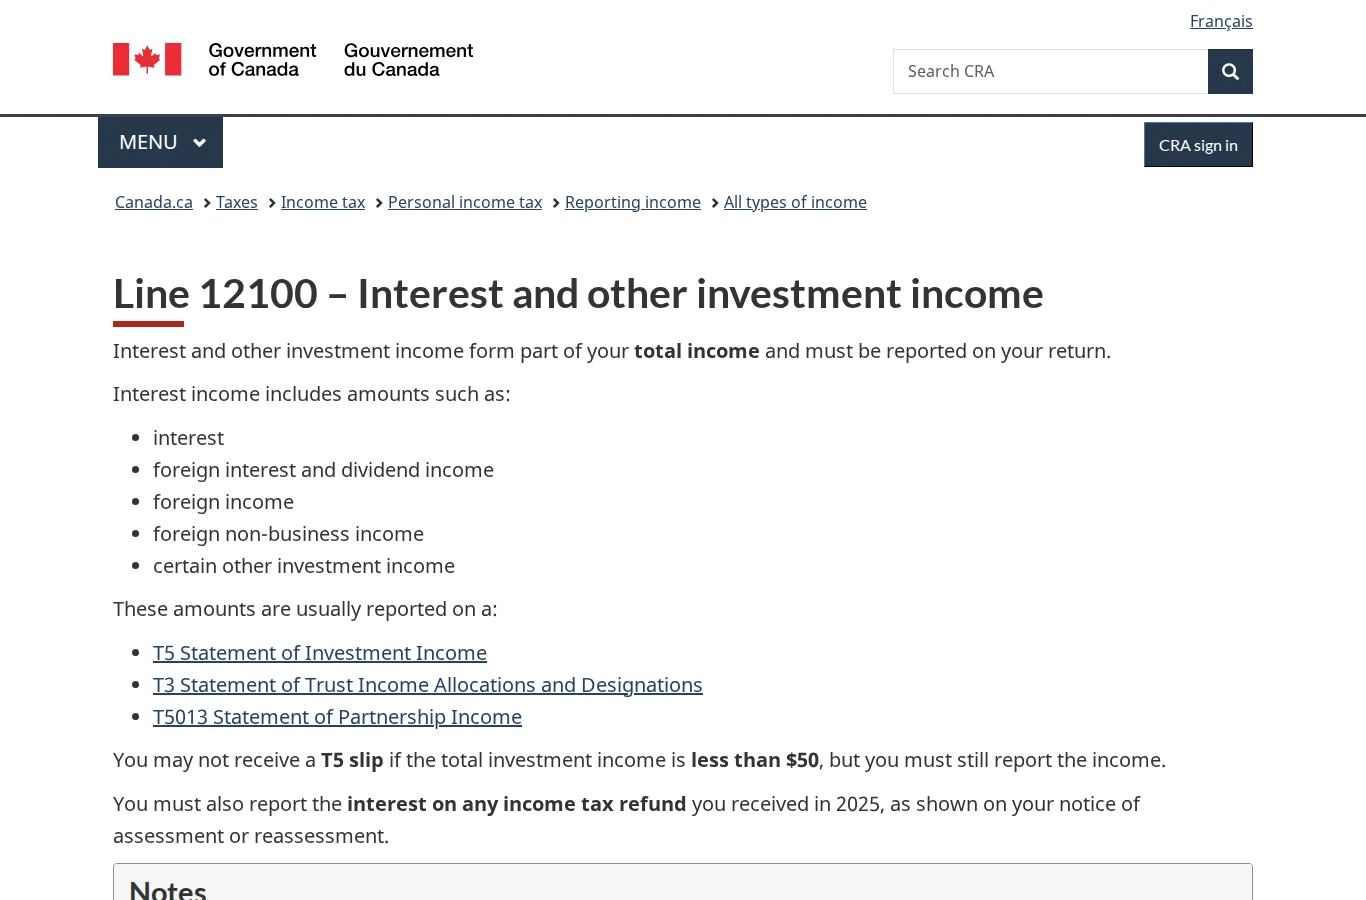
Your casino winnings stay tax-free. Once you put them in a savings account, though, the interest they earn becomes taxable investment income. The CRA requires you to report interest on line 12100 of your return.
The CAD 50 threshold for T5 slips often confuses people. That threshold determines only whether a financial institution issues you a slip; your obligation to report the interest doesn’t depend on it. Even if no T5 arrives because your interest fell under CAD 50, you still owe tax on it. This includes small amounts spread across multiple accounts. CAD 20 here, CAD 15 there, CAD 12 somewhere else. Each institution skips the slip, but the total belongs on your return.
Interest earned on winnings sitting in a casino account or a high-interest savings account is taxable the same way. The win itself is tax-free. The interest it generates counts as investment income. Keep track of it, because the CRA does.
Where the New Federal Tax Brackets Land If You Are a Professional
If the CRA classifies your gambling as a business, your winnings become taxable business income at your marginal rate. The federal brackets, with the bottom rate now lower, are below:
| 2026 Federal Tax Bracket | Income Range |
| 14% | Up to CAD 58,523 |
| 20.5% | CAD 58,523 to CAD 117,045 |
| 26% | CAD 117,045 to CAD 181,440 |
| 29% | CAD 181,440 to CAD 258,482 |
| 33% | Above CAD 258,482 |
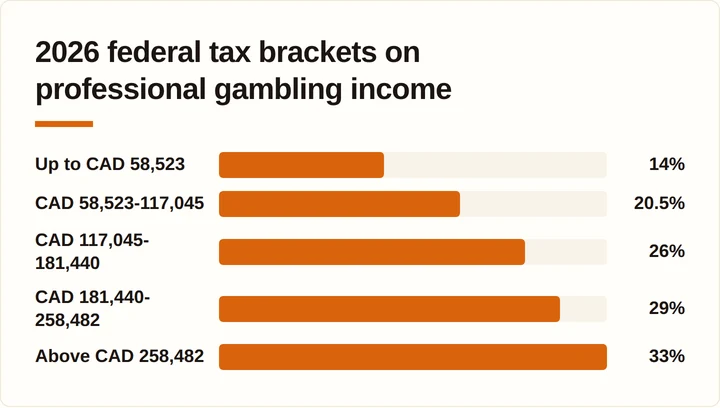
The federal Basic Personal Amount rose to CAD 16,452 for this year, up from CAD 16,129 in the prior year. Income at or below that amount owes no federal tax. Provinces add their own brackets on top, so the total rate depends on where you live.
Consider a professional gambler earning CAD 100,000 in taxable winnings. The federal tax would be 14% on the first CAD 58,523 and 20.5% on the remainder, before provincial tax. That’s a meaningful bill, and it’s why the recreational-versus-professional distinction matters so much.
Recreational players never see these brackets touch their winnings. The rates only apply when gambling is classified as a business. For everyone else, the statute keeps the gain at nil.
Ontario’s Record iGaming Market Doesn’t Change the Tax Answer
Ontario’s regulated online casino market keeps setting monthly revenue records. The province’s monthly revenue climbed steadily through the middle of the year:
Ontario Online Casino Revenue, 2026
| Month | Revenue | Notes |
| May | CA$326.4 million | — |
| June | CA$316.8 million | — |
| July | CA$330.4 million | new record, up 30.9% YoY from CA$252.4 million (July 2025) |
The province topped CAD 2 billion in total iGaming revenue for this year by the end of July.
That growth doesn’t change the tax answer. Market size and tax treatment are separate questions. The volume of play has grown fast. Recreational tax-free treatment stays uniform nationwide regardless. Whether you play at a regulated Ontario casino or a site based elsewhere, the same federal rules apply.
The clarity around professional play has sharpened. With more players and bigger volumes, the CRA has more data and more incentive to scrutinize frequent winners. If your play looks systematic and profitable, expect questions.
For players who ARE classified as professional, the business-expense rules offer some relief. Deductible expenses include:
- Travel to tournaments and casinos
- Tournament buy-ins and entry fees
- Poker or analysis software
- Professional fees for accountants or tax preparers
These deductions reduce your taxable business income; they don’t change the classification. If you’re a professional, you’re taxed on net earnings only.
FAQ
Do I need to report small casino wins on my tax return?
No. Recreational gambling winnings are tax-free under the Act’s nil-gain rule on gambling winnings, regardless of amount. A CAD 10 win and a CAD 100,000 win get the same treatment, as long as gambling isn’t your business. You don’t report either one.
Can I deduct my gambling losses?
Only if your gambling is classified as a business. Professional gamblers can deduct losses against business income, subject to the same rules as any other business. Recreational players cannot deduct losses, because there’s no taxable income to offset.
What makes someone a professional gambler for tax purposes?
The *Fournier-Giguère* ruling applied the *Stewart* framework, weighing intention to profit, commercial organization, sustained profitability, financial dependence, systematic high-volume play, and lifestyle evidence. The Supreme Court refused leave to appeal in June of this year, so this remains the current test. No single factor decides it. The CRA looks at the whole picture.
Are poker tournament winnings taxed differently than slot winnings?
No. The game doesn’t matter for tax purposes. What matters is whether the activity constitutes a business. A recreational poker player who wins a tournament pays no tax. A professional poker player who wins the same tournament pays tax as business income. The *Fournier-Giguère* players were poker players, but the same logic would apply to a professional sports bettor or a professional blackjack player.
Bylaw Desk — editorial byline